How Graduated Payment Mortgages Affect Your Credit Score
In the landscape of real estate financing, prospective homeowners are often faced with a myriad of mortgage options, each tailored to different financial situations. Among these options lies the Graduated Payment Mortgage (GPM), a lesser-known yet highly beneficial choice for borrowers seeking flexibility in their home financing journey. In this article, we will delve into the intricacies of the Graduated Payment Mortgage, exploring its mechanics, advantages, and considerations Can you use VA loan more than once for potential borrowers.
Understanding the Graduated Payment Mortgage:
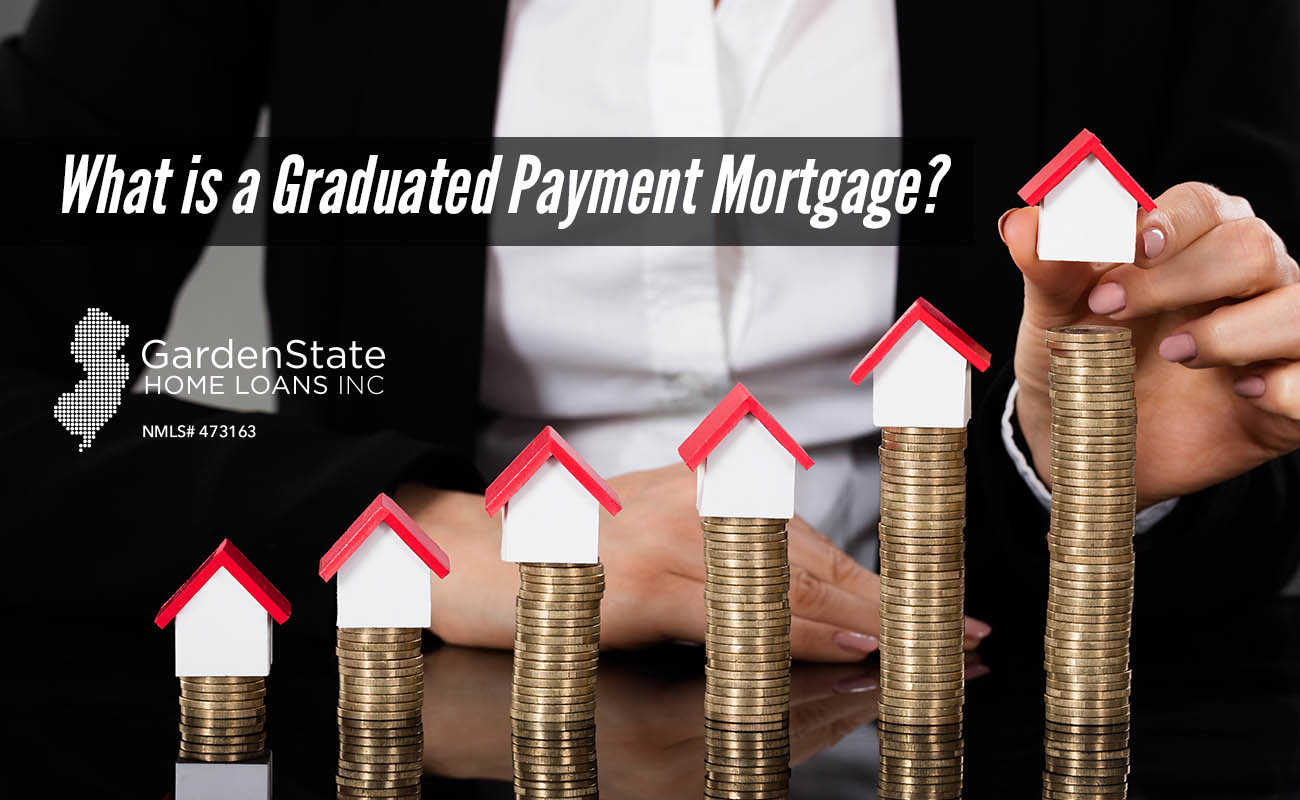
The Graduated Payment Mortgage is a specialized type of home loan that offers borrowers a unique payment structure. Unlike traditional fixed-rate mortgages, where monthly payments remain constant over the loan term, GPMs feature a graduated repayment plan. This means that initial payments start low and gradually increase over time, typically in intervals of several years.
How Graduated Payment Mortgages Work:
The hallmark of a Graduated Payment Mortgage lies in its phased payment schedule. In the early years of the loan term, borrowers benefit from lower monthly payments, providing financial flexibility during the initial stages of homeownership. These initial payments are deliberately set below what would be required to fully amortize the loan over its term.
As time progresses, usually every few years, the monthly payments increase. This gradual escalation continues until the payments reach a level that fully amortizes the loan by the end of the term. The purpose of this gradual increase is to align with the borrower’s anticipated income growth, enabling them to manage higher payments as their financial situation improves.
Benefits of Graduated Payment Mortgages:
- Initial Affordability: GPMs offer lower initial monthly payments compared to traditional fixed-rate mortgages, making homeownership more accessible, particularly for first-time buyers or those with limited financial resources.
- Alignment with Income Growth: The graduated payment structure of GPMs accommodates borrowers expecting their income to increase over time. As their earning potential grows, borrowers can manage higher monthly payments, ultimately leading to full loan repayment.
- Flexibility and Adaptability: Borrowers benefit from a repayment plan that evolves with their financial circumstances. The phased payment schedule provides predictability and allows borrowers to plan for future payment increases accordingly.
Considerations for Potential Borrowers:
While Graduated Payment Mortgages offer numerous benefits, there are important considerations for borrowers to keep in mind:
- Total Interest Payments: Despite initial affordability, borrowers may end up paying more in total interest over the life of the loan compared to fixed-rate mortgages. The extended period of lower payments can result in higher overall interest costs.
- Anticipation of Payment Increases: Borrowers must prepare for the gradual increase in monthly payments over time. Assessing whether future income growth aligns with payment adjustments is essential to avoid financial strain.
- Availability and Eligibility: GPMs may not be offered by all lenders, and eligibility criteria may vary. Borrowers should research and consult with mortgage professionals to determine if a GPM is suitable for their financial situation.
In Conclusion:
The Graduated Payment Mortgage offers a flexible and adaptable approach to homeownership, providing borrowers with a structured repayment plan that evolves with their financial capabilities. By offering initial affordability and aligning with anticipated income growth, GPMs empower borrowers to navigate the complexities of real estate financing with confidence. However, it’s crucial to carefully weigh the benefits and considerations before opting for a GPM to ensure that it aligns with your long-term financial goals. With proper research and guidance, Graduated Payment Mortgages can serve as a valuable tool on your journey to homeownership.

One Comment
John